Section 80D Health Insurance Tax Benefits 2026: Complete Guide
Save up to ₹75,000 extra in tax deductions beyond 80C. Most Indians miss this benefit. Here's how to maximize your health insurance tax savings.
Summarize with AI:
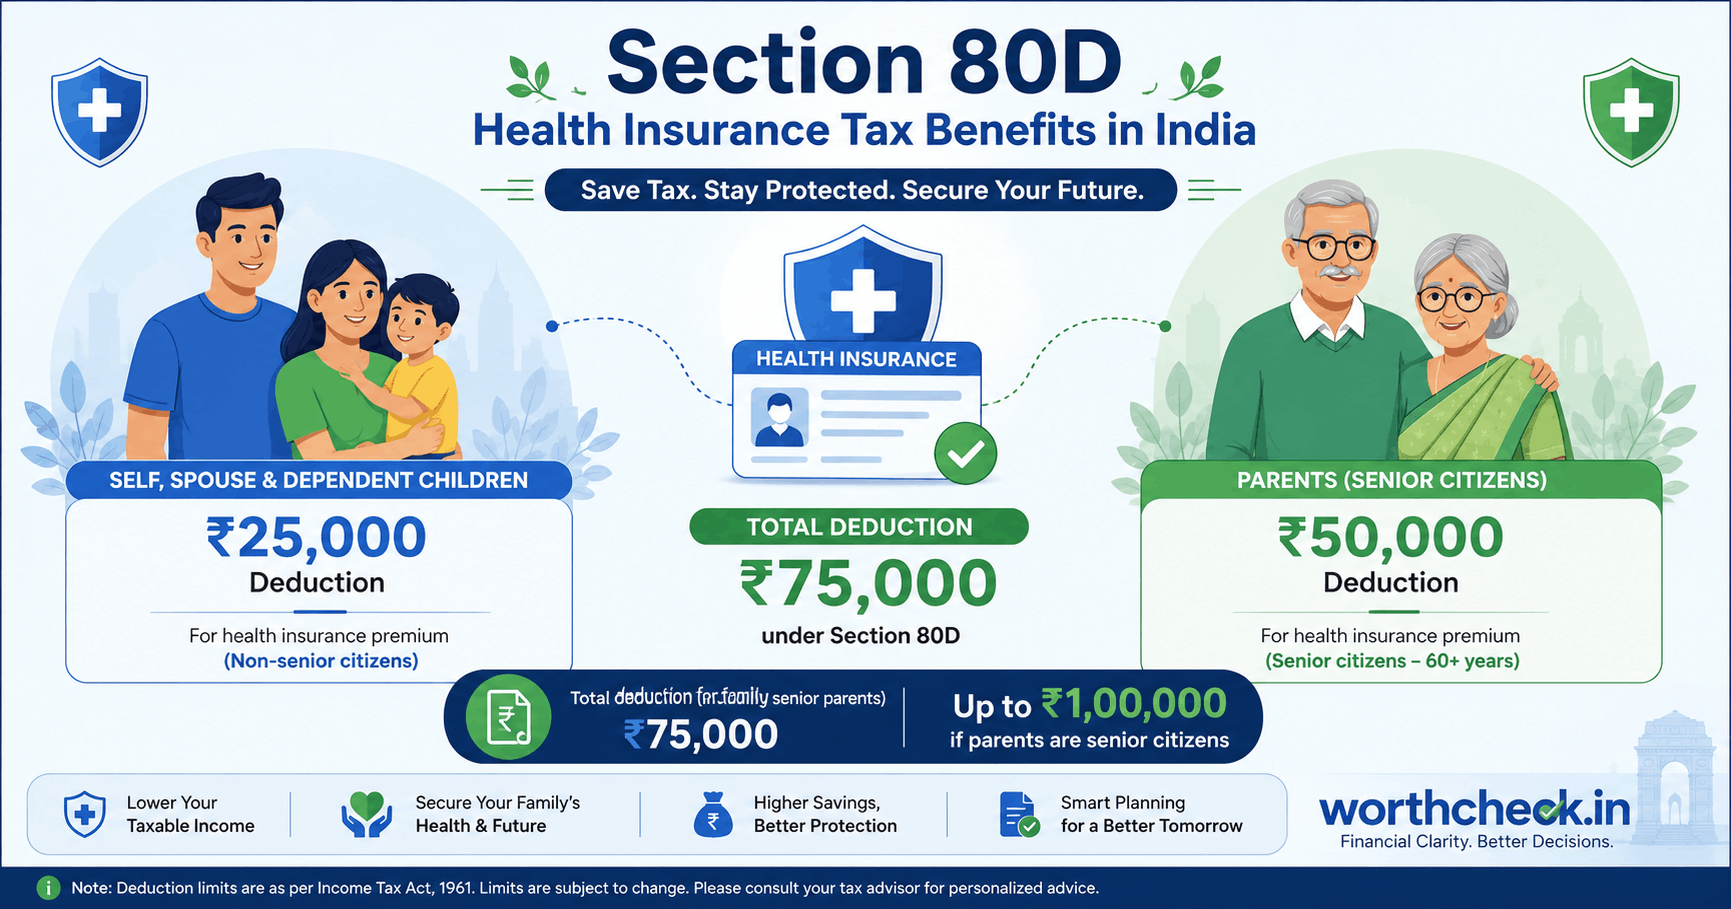
Key Takeaways: Section 80D Benefits
- ✓Extra deduction: Section 80D is ADDITIONAL to Section 80C. You can claim both!
- ✓Self & Family: Up to ₹25,000/year (₹50,000 if you're 60+)
- ✓Parents: Additional ₹25,000-₹50,000 for parents' insurance
- ✓Preventive checkup: ₹5,000 included even without insurance
- ✓Max possible: ₹1,00,000/year if both you and parents are 60+
⚠️ Important Disclaimer
This article is for educational purposes only and should not be considered financial advice. Past performance does not guarantee future results. Mutual fund investments and other financial products are subject to market risks. Please read all scheme information documents carefully before investing. We strongly recommend consulting a certified financial planner (CFP), registered investment advisor (RIA), or qualified financial professional for personalized guidance tailored to your specific financial situation.
🧮 Section 80D Calculator
Max limit: ₹25,000
Max: ₹5,000 (included in overall limit)
Your 80D Benefit
Tax Saved
In 30% bracket + 4% cess
Maximum possible: ₹25,000/year
Here's something that frustrates me: Most Indians know about Section 80C. They max it out every year with ELSS, PPF, or EPF. But ask them about Section 80D, and you'll get blank stares.
This is money left on the table. Section 80D can give you up to ₹75,000 in additional deductionsbeyond 80C. If you're in the 30% tax bracket, that's ₹23,400 in tax savings every single year. For senior citizens, the numbers are even better.
In this guide, I'll explain everything you need to know about Section 80D: who can claim it, how much you can save, and the exact steps to maximize your benefit.
TL;DR - Section 80D Limits at a Glance
| Scenario | Self & Family | Parents | Total Deduction | Tax Saved (30%) |
|---|---|---|---|---|
| You (<60) + No Parents | ₹25,000 | - | ₹25,000 | ₹7,800 |
| You (<60) + Parents (<60) | ₹25,000 | ₹25,000 | ₹50,000 | ₹15,600 |
| You (<60) + Parents (60+) | ₹25,000 | ₹50,000 | ₹75,000 | ₹23,400 |
| You (60+) + Parents (60+) | ₹50,000 | ₹50,000 | ₹1,00,000 | ₹31,200 |
Important: Preventive health checkup of ₹5,000 is included within these limits, not additional. Also, 80D is available in both Old and New tax regimes - but only employer NPS contribution (80CCD(2)) is allowed in New Regime, not 80D. Choose Old Regime to claim 80D.
What is Section 80D?
Section 80D of the Income Tax Act allows you to claim tax deductions on health insurance premiums and preventive health checkups. Unlike Section 80C which covers investments, 80D specifically covers your healthcare expenses.
What 80D Covers
- ✓ Health insurance premiums
- ✓ Critical illness riders
- ✓ Preventive health checkups
- ✓ Top-up health plans
- ✓ Super top-up plans
- ✓ Multi-year premium payments
What 80D Does NOT Cover
- ✗ Life insurance premiums (use 80C)
- ✗ Personal accident policies
- ✗ Cash payments (must be digital/cheque)
- ✗ Medical expenses (unless specified)
- ✗ Group insurance paid by employer
Key Point: 80D is ADDITIONAL to 80C
Many people think 80D is part of the 80C limit. It's not. You can claim the full ₹1.5 lakh under 80C AND the full 80D limit separately. If you're in the 30% bracket and claim both: ₹46,800 (80C) + ₹23,400 (80D for parents 60+) = ₹70,200 in tax savings.
Section 80D Deduction Limits 2026 (FY 2025-26 / AY 2026-27)
The limits depend on two factors: who you're insuring and their age. Here's the complete breakdown:
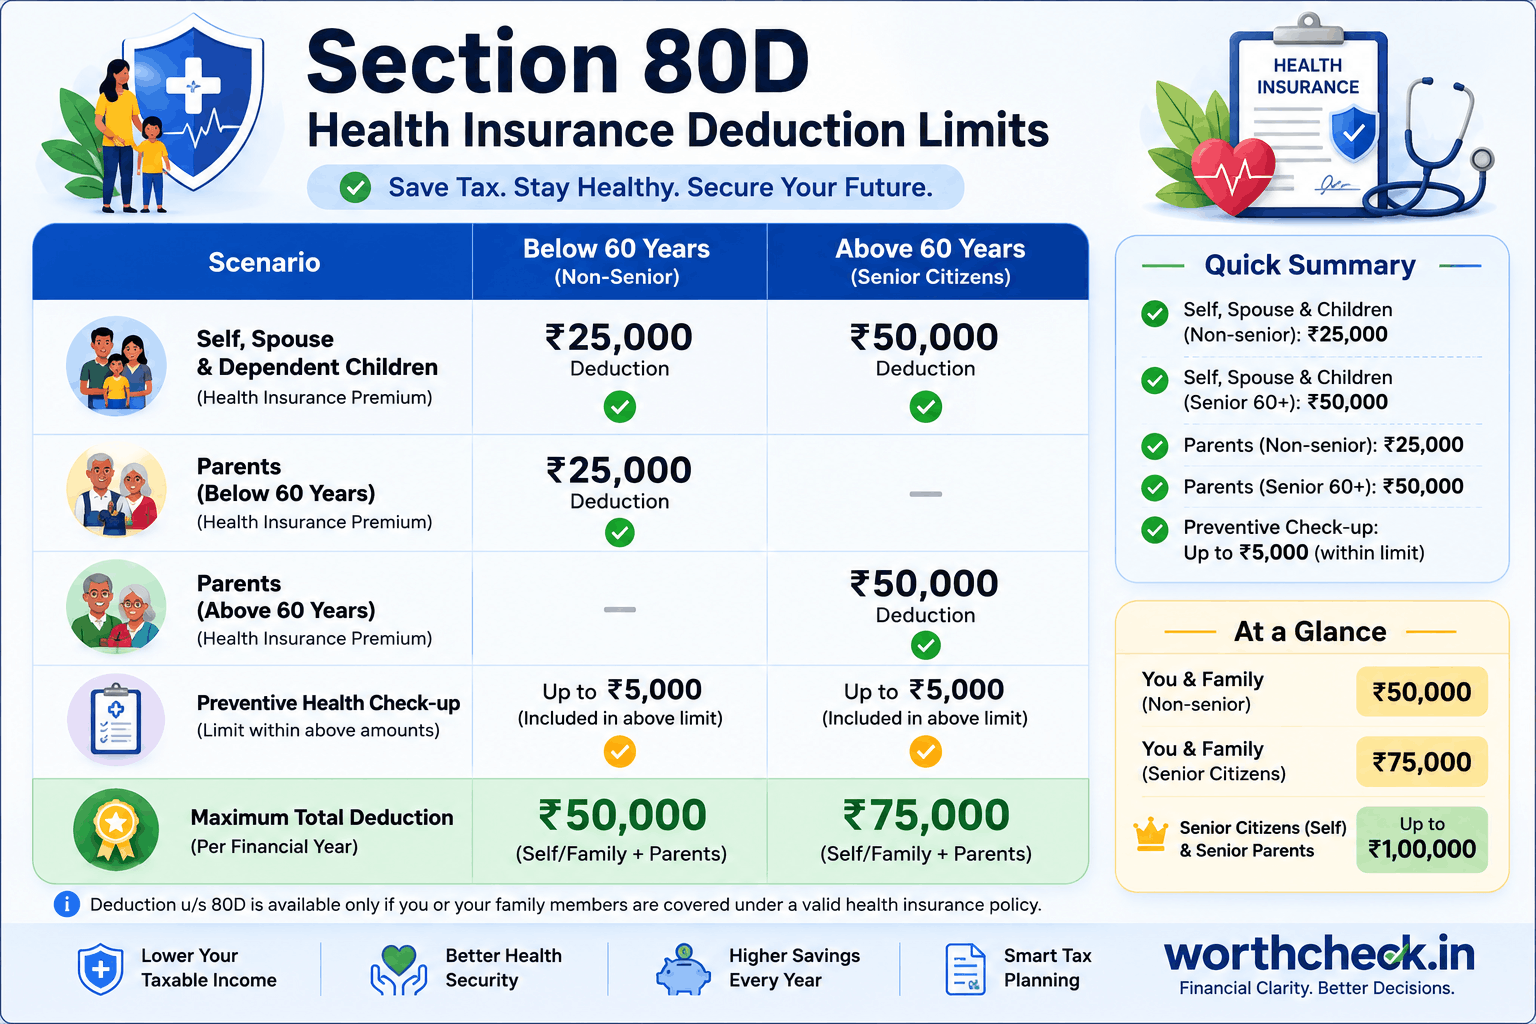
For Self, Spouse & Children
If You're Below 60
Covers health insurance for you, your spouse, and dependent children
If You're 60 or Above
Higher limit for senior citizens to account for higher premiums
For Parents (Additional Deduction)
Parents Below 60
Additional deduction if you pay for parents' health insurance
Parents 60 or Above
Higher limit for senior citizen parents
Preventive Health Checkup
₹5,000 per family
You can claim up to ₹5,000 for preventive health checkups for yourself, spouse, children, or parents. This amount is included within your 80D limit, not additional.
Pro tip:Even if you don't have health insurance, you can claim ₹5,000 for health checkups. Many people miss this!
Who Can Claim Section 80D?
| Insured Person | Can Claim? | Condition |
|---|---|---|
| Self | Yes | Always eligible |
| Spouse | Yes | Even if spouse has own income |
| Dependent Children | Yes | Must be financially dependent |
| Parents | Yes | Additional limit, even if parents have income |
| In-laws | No | Your spouse can claim for their parents |
| Siblings | No | Not covered under 80D |
| Grandparents | No | Only parents, not grandparents |
HUF Note:If you're part of a Hindu Undivided Family (HUF), the HUF can claim 80D for any member of the HUF. This is separate from individual claims.
What Expenses Qualify Under 80D?
Health Insurance Premiums
- ✓Individual health insurance: Policies like Star Health, HDFC Ergo, ICICI Lombard, etc.
- ✓Family floater plans: Single policy covering entire family
- ✓Critical illness policies: Cancer, heart disease, etc.
- ✓Top-up and Super top-up plans: Additional coverage above base policy
- ✓Multi-year premium: Proportionate deduction each year
✨ Good News (Sep 2025): GST on individual health insurance premiums has been removed since September 22, 2025. The entire premium you pay now qualifies for 80D deduction with no GST component to worry about.
Preventive Health Checkups
- ✓Annual health checkups: Full body checkup packages
- ✓Specific tests: Blood tests, ECG, X-rays when done preventively
- ✓Cancer screening: Mammograms, colonoscopy, etc.
Medical Expenditure for Senior Citizens (No Insurance)
Special Rule for Very Senior Citizens
If your parents are 80 years or above and don't have health insurance (many insurers won't cover them), you can claim up to ₹50,000 for actual medical expenses incurred. Keep all bills and prescriptions as proof.
Senior Citizens: Special Rules Under 80D
Senior citizens get enhanced benefits under Section 80D. Here's what you need to know:
| Age Category | Definition | Limit | Special Benefit |
|---|---|---|---|
| Senior Citizen | 60-79 years | ₹50,000 | Higher deduction limit |
| Very Senior Citizen | 80+ years | ₹50,000 | Can claim for medical expenses even without insurance |
Age Determination
Your age is determined as of the last day of the financial year. So if you turn 60 on March 31, 2026, you're eligible for the senior citizen limit (₹50,000) for FY 2025-26.
Real-Life Calculation Examples
Example 1: Young Professional (Age 32)
Situation:
- • Rahul, 32, unmarried
- • Annual CTC: ₹15 lakhs
- • Health insurance: ₹18,000/year
- • Parents (both 58): ₹22,000/year
- • Annual checkup: ₹4,000
80D Calculation:
- Self premium: ₹18,000 (limit ₹25,000) = ₹18,000
- Parents premium: ₹22,000 (limit ₹25,000) = ₹22,000
- Checkup: ₹4,000 (limit ₹5,000) = ₹4,000
- Total 80D: ₹44,000
- Tax saved (20% bracket): ₹9,152
Example 2: Family with Senior Parents (Age 45)
Situation:
- • Priya, 45, married with 2 kids
- • Annual CTC: ₹28 lakhs
- • Family floater: ₹32,000/year
- • Father (68): ₹48,000/year
- • Mother (65): included in father's policy
- • Annual checkup (family): ₹8,000
80D Calculation:
- Family floater: ₹32,000 but limit ₹25,000 = ₹25,000
- Parents (60+): ₹48,000 (limit ₹50,000) = ₹48,000
- Checkup: ₹5,000 max (₹8,000 spent) = ₹2,000 (remaining from limits)
- Total 80D: ₹75,000
- Tax saved (30% bracket): ₹23,400
* Preventive checkup amount that fits within remaining limits
Example 3: Senior Citizen with Very Senior Parents
Situation:
- • Sharma ji, 62, retired
- • Pension income: ₹12 lakhs
- • His health insurance: ₹55,000/year
- • Mother (85): No insurance, medical bills ₹65,000
80D Calculation:
- Self (60+): ₹55,000 but limit ₹50,000 = ₹50,000
- Parent (80+) medical: ₹65,000 but limit ₹50,000 = ₹50,000
- Total 80D: ₹1,00,000
- Tax saved (30% bracket): ₹31,200
This is the maximum possible 80D deduction! ₹1 lakh when both you and your parents are senior citizens.
6 Common Mistakes to Avoid
1. Paying in Cash
Health insurance premiums paid in cash are NOT eligible for 80D deduction. Always pay via bank transfer, cheque, UPI, or card. Only preventive checkups allow cash payments up to ₹5,000.
2. Confusing 80C and 80D
Life insurance premiums go under 80C (up to ₹1.5L). Health insurance goes under 80D (separate limit). Don't mix them up or you'll lose deductions.
3. Claiming New Regime Benefits
Section 80D is NOT available in the New Tax Regime. If you've opted for the new regime, you can't claim 80D. Evaluate which regime saves you more tax.
4. Not Insuring Parents
If your parents are 60+, you can get ₹50,000 additional deduction. Even if they have their own income, you can pay the premium and claim the deduction.
5. Forgetting Preventive Checkups
Many people don't know they can claim ₹5,000 for health checkups even without insurance. Keep those diagnostic bills!
6. Multi-year Premium Confusion
If you pay 3 years of premium upfront, divide it by 3 and claim proportionate amount each year. You can't claim the entire amount in one year.
How to Claim Section 80D Deduction
Step-by-Step Process
Collect Documents
Gather premium receipts, policy documents, and checkup bills. Ensure payment was made digitally (not cash for premiums).
Submit to Employer (If Salaried)
Submit investment declaration (usually in Feb-March) with proof of health insurance premiums. TDS will be adjusted accordingly.
File ITR with 80D Details
In your Income Tax Return, enter 80D deduction under "Deductions" section. ITR-1 and ITR-2 both have dedicated fields for this.
Keep Records for 6 Years
Store all receipts and bank statements. The IT department can ask for proof during assessment for up to 6 years.
Documents Required
For Health Insurance
- • Premium payment receipt
- • Policy document (first page)
- • Bank statement showing payment
- • Certificate from insurer (Form 16B)
For Preventive Checkup
- • Hospital/diagnostic center bills
- • Payment receipt (cash allowed here)
- • Doctor prescription (if any)
Frequently Asked Questions (FAQs)
Can I claim 80D if I'm on the New Tax Regime?
No. Section 80D deduction is not available under the New Tax Regime. Only employer's NPS contribution (80CCD(2)) is allowed. If you have significant health insurance premiums, consider staying with the Old Regime.
Can I claim 80D for in-laws?
No. You can only claim 80D for your own parents, not in-laws. However, your spouse can claim for their parents separately. So if both spouses work, one claims for their parents and the other for theirs.
Is employer-provided group health insurance counted under 80D?
No. Group insurance provided by employer is a perk, not your expense. You can't claim it under 80D. Only the premium you pay qualifies for deduction.
Can I claim 80D if my parents have their own income?
Yes! Unlike some other deductions, there's no income limit for parents. Even if your parents have their own income and file returns, if you pay their premium, you can claim the deduction.
What if I pay for 3 years premium in one year?
Divide the premium by the number of years covered. For example, if you pay ₹75,000 for 3 years, claim ₹25,000 each year (subject to limits). Keep proof of the multi-year payment.
Is GST on premium eligible for 80D?
Yes. The total premium amount including GST (18%) qualifies for 80D deduction. So if your premium is ₹21,240 (₹18,000 + 18% GST), you can claim the full ₹21,240.
Can I claim for top-up health insurance?
Yes. Both top-up and super top-up health insurance premiums qualify for 80D deduction, within the overall limit.
What if my premium exceeds the limit?
You can only claim up to the limit. For example, if you pay ₹35,000 premium and you're below 60, you can only claim ₹25,000. The remaining ₹10,000 provides no tax benefit.
Can I claim 80D for adult children?
Only if they are financially dependent on you. Adult children who earn their own income should file their own returns and claim their own 80D deduction.
Is OPD insurance premium covered under 80D?
Yes. OPD (outpatient department) insurance, which covers doctor visits and minor treatments, qualifies for 80D deduction.
Can I claim preventive checkup even without health insurance?
Yes!Even if you don't have health insurance, you can claim up to ₹5,000 for preventive health checkups. This is a separate benefit.
What documents do I need for 80D claim?
Premium payment receipts, policy documents, bank statements showing digital payment, and for preventive checkups - hospital bills. Keep all documents for 6 years.
Can both spouses claim 80D?
If both spouses have income, each can claim their share. For example, if a family floater costs ₹30,000, one spouse can claim ₹25,000 and the other ₹5,000. Or one can pay parents' premium.
Does critical illness insurance qualify for 80D?
Yes. Critical illness riders and standalone critical illness policies qualify for 80D deduction, within the overall limit.
When should I buy health insurance for maximum 80D benefit?
Buy at the start of the financial year (April) to get the full benefit for that year. If you buy in March, you only get 1 month of premium as deduction that year.
Final Verdict: Don't Leave Money on the Table
Section 80D is one of the most underutilized tax-saving opportunities in India. If you're in the 30% tax bracket with senior citizen parents, you're potentially losing ₹23,400 every year by not claiming this benefit.
Your Action Plan:
- Get health insurance if you don't have one (protects you AND saves tax)
- Insure your parents - especially if they're 60+ (higher deduction limit)
- Schedule annual preventive health checkups (additional ₹5,000 deduction)
- Pay all premiums digitally (cash payments don't qualify)
- Keep records for 6 years for any IT department queries