Written by Sid Joshi
Founder, WorthCheck.in
Gold Investment India 2026: SGB vs Gold ETF vs Physical Gold
Gold prices have hit all-time highs. Your parents say buy gold, your financial advisor says avoid it. Who's right? I'll show you exactly how to invest in gold for maximum returns and minimum tax.
🏆 Quick Verdict
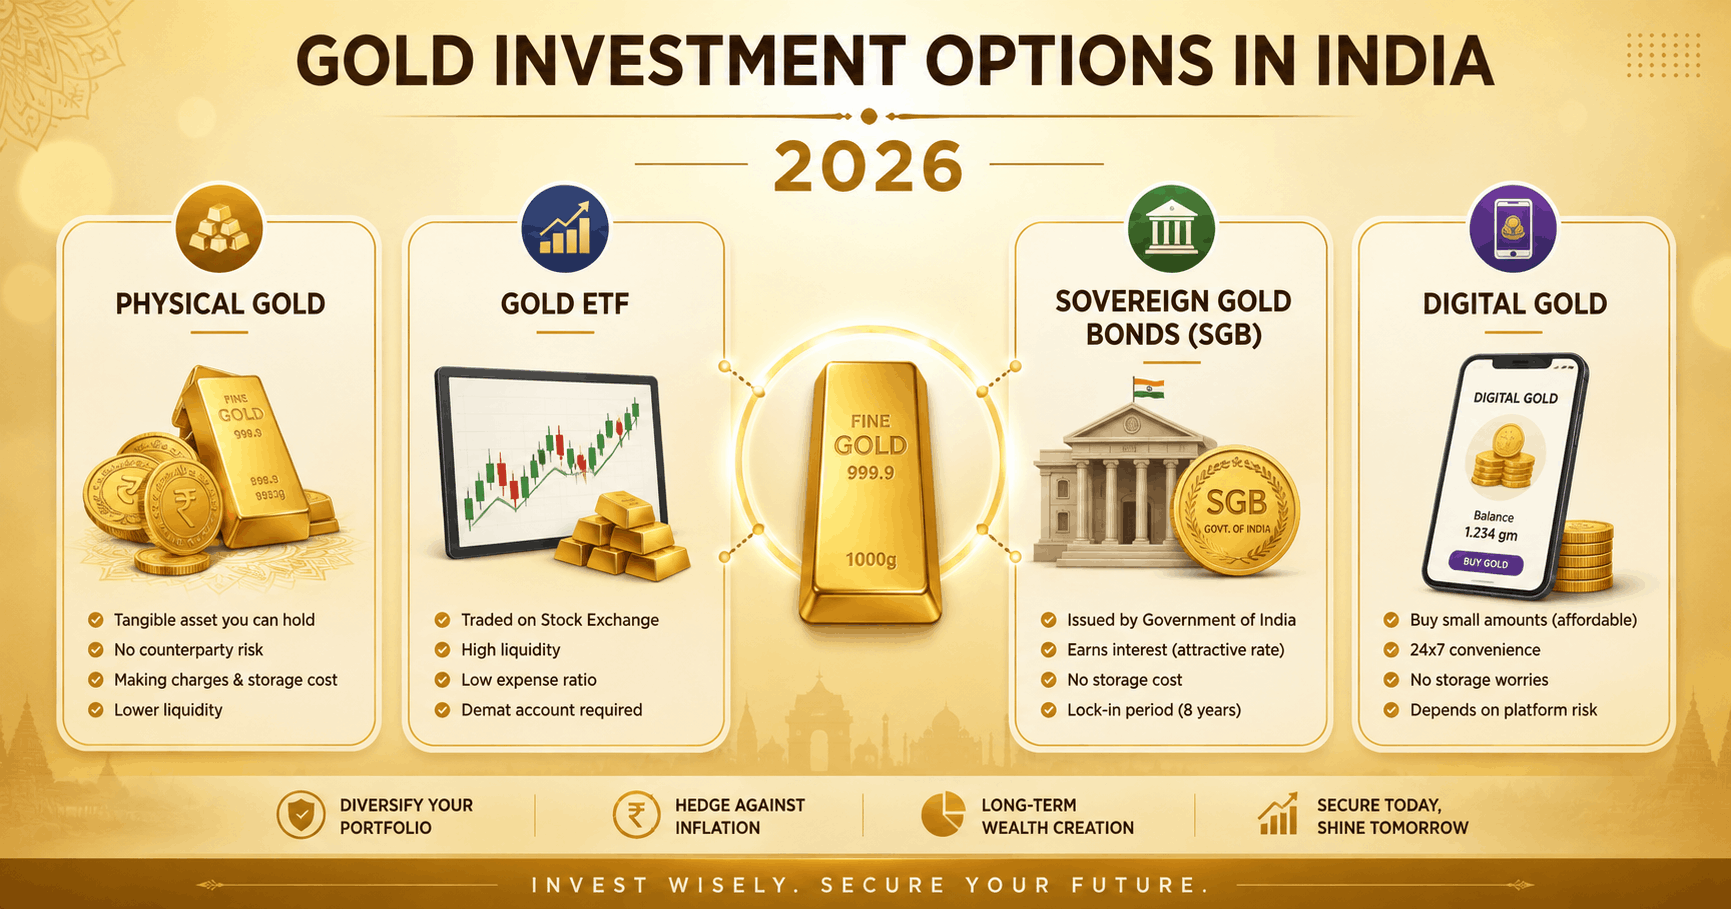
For long-term (8+ years): Sovereign Gold Bonds (SGB)
SGBs give you 2.5% yearly interest ON TOP of gold price appreciation. Tax exemption only if you buy during RBI's primary issuanceand hold till 8-year maturity (Budget 2026 change). Note: RBI hasn't issued new SGBs since Feb 2024.
For liquidity & trading: Gold ETFs
Need to buy/sell quickly? Gold ETFs trade on stock exchanges like stocks. Can also do SIP. Tax is 12.5% LTCG after 1 year (same as equity now).
For physical possession: Gold coins/bars from banks
Avoid jewelry for investment (10-25% making charges). If you must hold physical, buy 24K coins from banks with lowest premiums.
Key Takeaways
- ✓SGB is the best: 2.5% annual interest + zero LTCG tax (only if bought from RBI primary issuance & held to maturity). RBI hasn't issued new SGBs since Feb 2024.
- ✓Gold ETF for flexibility: Buy/sell anytime on stock exchange. 12.5% LTCG tax. Great for SIP.
- ✓Physical gold loses money: 3-8% making charges, storage costs, purity risk. Avoid for investment.
- ✓5-10% allocation: Gold should be max 5-10% of your portfolio. It's a hedge, not a growth asset.
- ✓Tax change 2024: Gold LTCG tax reduced from 20% to 12.5%. Holding period reduced from 36 to 24 months.
⚠️ Important Disclaimer
This article is for educational purposes only and should not be considered financial advice. Past performance does not guarantee future results. Mutual fund investments and other financial products are subject to market risks. Please read all scheme information documents carefully before investing. We strongly recommend consulting a certified financial planner (CFP), registered investment advisor (RIA), or qualified financial professional for personalized guidance tailored to your specific financial situation.
🥇 Gold Investment Calculator
Historical average: 9-11% in INR terms
Result: For 8 years at 10% growth, SGB gives the best returns. SGB wins because of 2.5% yearly interest + zero tax at maturity!
Why Should You Invest in Gold?
Let me be upfront: I don't think gold should be your primary investment. Equity mutual funds and real estate historically beat gold for wealth creation. But gold has a role to play.
Why Gold Makes Sense
- ✓ Hedge against inflation: When rupee falls, gold rises in INR
- ✓ Crisis protection: Gold does well when markets crash
- ✓ Negative correlation: Balances equity volatility
- ✓ Liquidity: Can sell anywhere in the world
- ✓ No credit risk: Gold is gold, unlike bonds
Gold's Limitations
- ✗ No income: Gold doesn't pay dividends (except SGB)
- ✗ Lower long-term returns: 9-10% vs equity's 12-15%
- ✗ Volatile: Can fall 20-30% in bad years
- ✗ No compounding: Just price appreciation
- ✗ Storage costs: Physical gold has risks
My view:Keep 5-10% of your portfolio in gold. It's insurance, not the main engine. Now let's see HOW to invest in gold most efficiently.
Sovereign Gold Bonds (SGB): The Smart Choice
Sovereign Gold Bonds are issued by the Government of India through RBI. They're the closest thing to "perfect" gold investment for Indians.
SGB Features
Why SGB is Best for Long-term
The SGB Math
Let's say gold price grows at 10% per year. Here's what happens to Rs 1 lakh over 8 years:
- Gold value at maturity: Rs 2,14,358
- + 2.5% interest for 8 years: Rs 20,000
- Total: Rs 2,34,358
- Tax on capital gains: Rs 0 (zero at maturity!)
- Net return: Rs 2,34,358 (134% gain)
SGB Downsides
- 8-year lock-in: Though you can exit after 5 years or sell on exchange
- Limited availability: RBI issues in tranches, not always available
- Low liquidity on exchange: Bid-ask spreads can be wide
- Interest is taxable: The 2.5% interest is added to your income
Critical (Budget 2026): To get the tax exemption, you MUST buy SGBs during RBI's primary issuance and hold till 8-year maturity. Buying from stock exchange means you pay 12.5% LTCG. Note: RBI has not issued new SGBs since February 2024. Check RBI website for future tranches.
Gold ETFs: Best for Flexibility
Gold ETFs (Exchange Traded Funds) are mutual funds that hold physical gold and trade on stock exchanges like stocks. Each unit represents a specific quantity of gold (usually 1 gram).
| Feature | Details |
|---|---|
| Minimum investment | 1 unit (~Rs 70-80) |
| Expense ratio | 0.4-0.6% per year |
| Trading | Buy/sell anytime during market hours |
| Demat required | Yes |
| LTCG tax | 12.5% (holding > 12 months) |
| SIP available | Yes (through brokers) |
Top Gold ETFs in India (2026)
Nippon India Gold ETF
- AUM: Rs 2,500+ crore
- Expense: 0.51%
- Most liquid gold ETF
HDFC Gold ETF
- AUM: Rs 2,000+ crore
- Expense: 0.48%
- Good liquidity
SBI Gold ETF
- AUM: Rs 1,800+ crore
- Expense: 0.50%
- Bank-backed trust
Kotak Gold ETF
- AUM: Rs 1,500+ crore
- Expense: 0.42%
- Lowest expense
Gold ETF vs Gold Mutual Fund:Gold mutual funds (Gold FoF) invest in gold ETFs. They don't require a demat account and allow SIP. But they have higher expense ratios (0.6-0.8%). If you have a demat, directly buy ETF.
Physical Gold: The Expensive Choice
I know, I know. Your grandmother's gold jewelry feels "real" in a way that paper investments don't. But if you're investing for returns, physical gold is the worst option.
The Hidden Costs of Physical Gold
- Making charges (3-25%): Jewelry charges 10-25%. Even coins have 3-8% premium.
- Purity risk: How do you know it's actually 24K? Hallmarking helps but isn't perfect.
- Storage costs: Bank locker costs Rs 2,000-15,000/year. Home storage has theft risk.
- Selling losses: Jewelers buy back at 5-10% below market. They don't pay for making charges.
- GST: 3% GST on purchase. Not recoverable on sale.
If You Must Buy Physical Gold
Some people have cultural or personal reasons to hold physical gold. If that's you, here's how to minimize losses:
1. Buy 24K Gold Coins from Banks
SBI, HDFC, ICICI banks sell 24K gold coins with lowest premiums (3-5%). Purity is guaranteed. Avoid jewelers.
2. Avoid Jewelry for Investment
Jewelry has 10-25% making charges that you NEVER recover. Buy jewelry for wearing, not investing.
3. Check BIS Hallmark
Look for BIS hallmark (HUID number). It certifies purity. Don't buy unhallmarked gold.
4. Keep Bills Forever
For capital gains calculation and proving legitimacy, keep purchase bills. IT department can ask.
Digital Gold: Convenient but Risky
Apps like Paytm, PhonePe, Google Pay offer "Digital Gold" where you can buy gold starting from Rs 1. It's convenient, but there are risks.
Digital Gold Pros
- ✓ Start from Rs 1
- ✓ No demat needed
- ✓ Instant buy/sell
- ✓ Can convert to physical
- ✓ 24K pure gold
Digital Gold Cons
- ✗ Not regulated by SEBI/RBI
- ✗ Platform risk (what if Paytm shuts down?)
- ✗ 3% GST on purchase
- ✗ Spread between buy/sell (1-2%)
- ✗ No interest like SGB
My recommendation: Use digital gold only for very small amounts or short-term holding. For serious gold investment, use SGB or Gold ETFs which are regulated and safer.
Complete Comparison: All Gold Options
| Feature | SGB | ETF | Physical | Digital |
|---|---|---|---|---|
| Minimum | 1g (~₹7.3K) | 1 unit (~₹70) | 0.5g (~₹3.6K) | ₹1 |
| Interest | 2.5%/yr | None | None | None |
| LTCG Tax | 0% | 12.5% | 12.5% | 12.5% |
| Lock-in | 5 yrs | None | None | None |
| Costs | Zero | 0.5%/yr | 3-25% | 3% GST |
| Liquidity | Low | High | Medium | High |
| Regulation | RBI | SEBI | BIS | None |
| Best For | Long-term | Trading | Jewellery | Small |
Gold Tax Rules 2026 (Post Budget 2024 Changes)
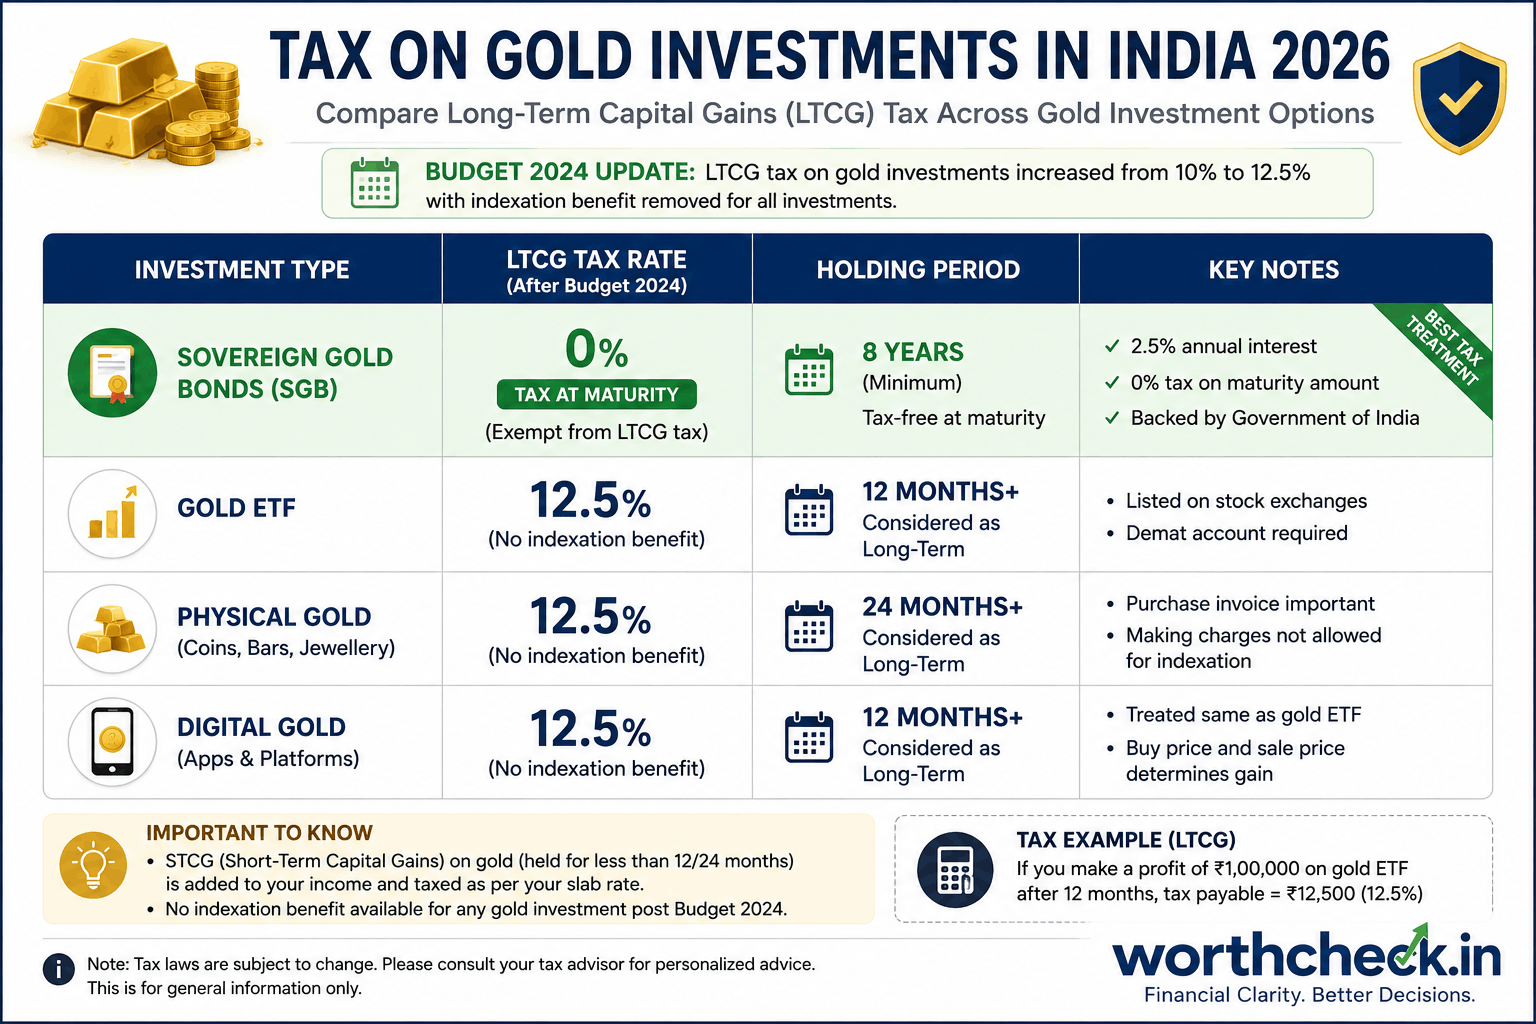
Budget 2024 simplified gold taxation significantly. Here are the current rules:
| Investment Type | LTCG Period | LTCG Tax | STCG |
|---|---|---|---|
| SGB (held to maturity) | 8 yrs | 0% | N/A |
| SGB (early exit) | 12 mo | 12.5% | Slab |
| Gold ETF / MF | 12 mo | 12.5% | Slab |
| Physical Gold | 24 mo | 12.5% | Slab |
| Digital Gold | 24 mo | 12.5% | Slab |
Key Tax Changes (Budget 2024)
- • LTCG tax reduced from 20% to 12.5% for all gold investments
- • Holding period for LTCG reduced from 36 months to 24 months (12 months for ETFs/SGBs)
- • Indexation benefit removed (but lower tax rate compensates)
⚠️ Budget 2026 Update: SGB Tax Rules Changed
- • Tax exemption at maturity only for original subscribers who hold till 8-year maturity
- • If you buy SGB from secondary market (stock exchange), you pay 12.5% LTCG even at maturity
- • Premature redemption (5-year window) is now taxable for everyone
- • These changes are effective from April 1, 2026
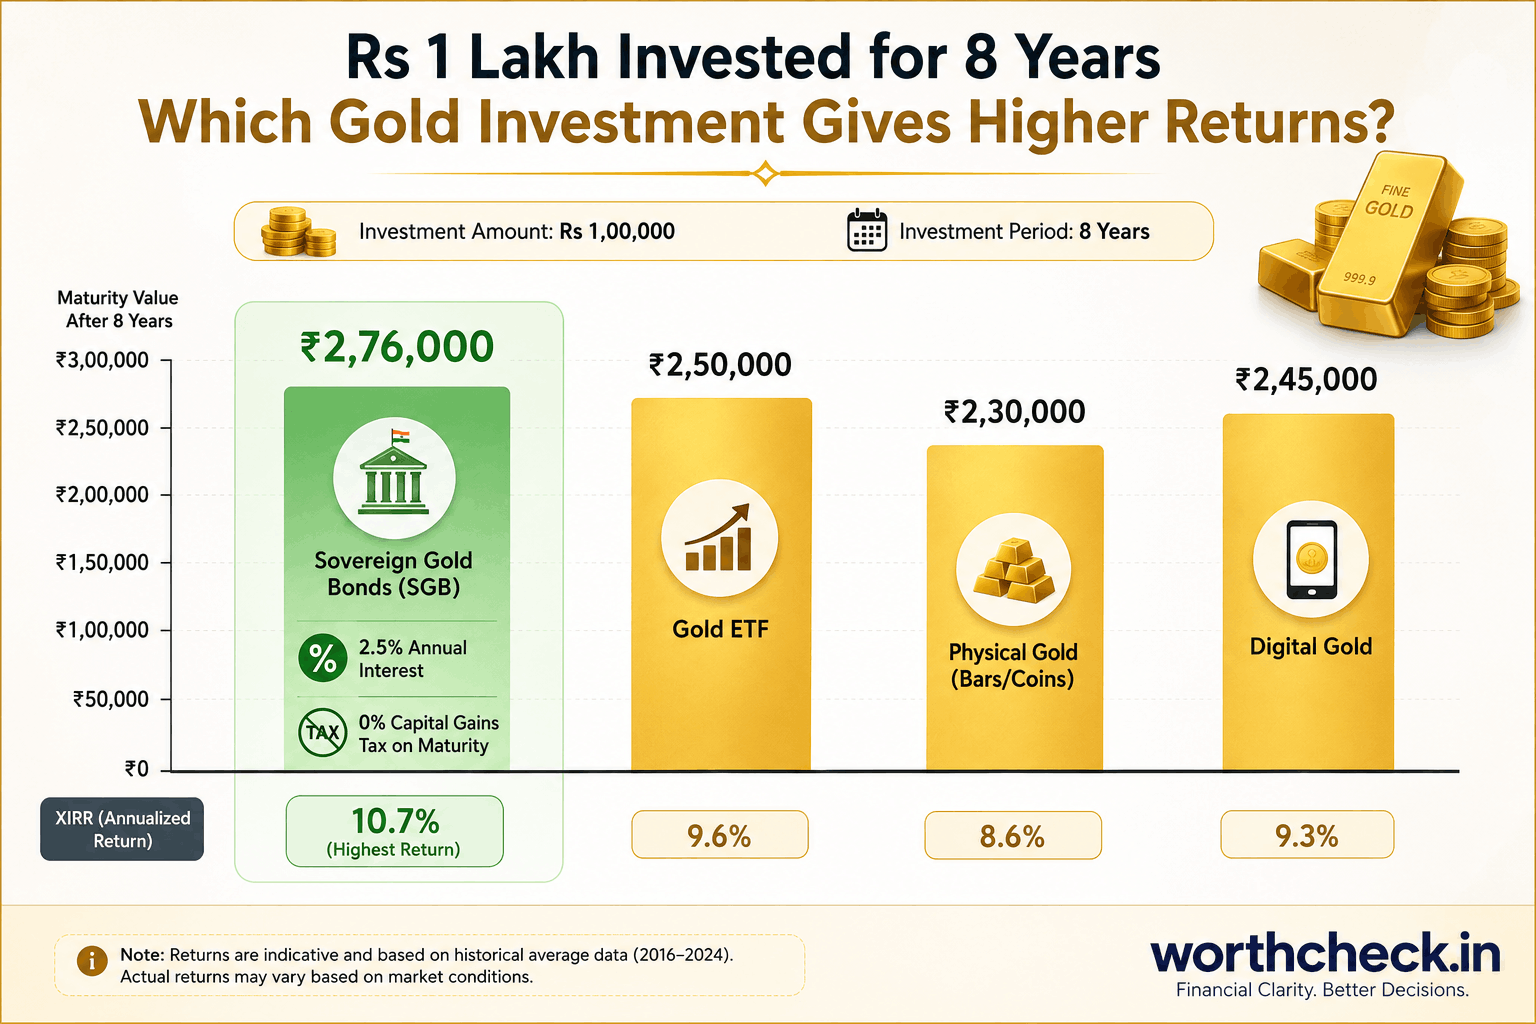
Real Example: Rs 1 Lakh Investment Over 8 Years
Let's assume gold grows at 10% per year (historical average in INR). Here's what happens to Rs 1,00,000:
🥇 SGB (Winner)
- Gold value (10% × 8 yrs):Rs 2,14,358
- Interest (2.5% × 8 yrs):Rs 20,000
- Total:Rs 2,34,358
- Tax:Rs 0
- Net Amount:Rs 2,34,358
📈 Gold ETF
- Gold value:Rs 2,14,358
- Expense ratio (0.5% × 8):-Rs 4,000
- Net before tax:Rs 2,10,358
- Tax (12.5% on gains):-Rs 13,795
- Net Amount:Rs 1,96,563
🪙 Physical Gold
- Initial (minus 5% making):Rs 95,000
- Growth (10% × 8 yrs):Rs 2,03,640
- Tax (12.5% on gains):-Rs 13,580
- Net Amount:Rs 1,90,060
📱 Digital Gold
- Initial (minus 3% GST):Rs 97,000
- Growth (10% × 8 yrs):Rs 2,07,927
- Tax (12.5% on gains):-Rs 13,866
- Net Amount:Rs 1,94,061
Verdict: SGB gives you Rs 37,795 more than Gold ETF, and Rs 44,298 morethan Physical Gold. Over 8 years, that's a 20% higher return!
How to Buy Each Type of Gold
🏛️ Sovereign Gold Bonds
- Wait for RBI announcement (4-5 tranches per year)
- Apply through your bank's net banking, or
- Apply through brokers like Zerodha, Groww, HDFC Securities
- Apply online for Rs 50/gram discount
- Bonds credited to your demat within 2 weeks
⚠️ Note: RBI hasn't issued new SGBs since Feb 2024. You can buy on NSE/BSE, but you'll pay 12.5% LTCG at maturity (no tax exemption for secondary market buyers per Budget 2026)
📈 Gold ETF
- Open a demat account (Zerodha, Groww, Upstox, etc.)
- Search for gold ETF (e.g., GOLDBEES, HDFCGOLD)
- Buy units like you buy stocks
- Set up SIP if you want regular investment
🪙 Physical Gold
- Visit a bank branch (SBI, HDFC, ICICI)
- Buy 24K gold coins (1g, 2g, 5g, 10g available)
- Get invoice and purity certificate
- Store in bank locker or home safe
Avoid: Jewelry stores for investment gold
How Much Gold Should You Hold?
Gold is a hedge, not a growth asset. Most financial advisors recommend keeping gold to 5-10% of your total portfolio.
If you're young and have long horizon
Good for most investors
Only if expecting crisis/inflation
My allocation:I keep about 7-8% in gold (mostly SGBs). The rest is in equity mutual funds, PPF, and some real estate. Gold is my "insurance" for when everything else falls.
Frequently Asked Questions
Is SGB better than Gold ETF?
For 8+ years, SGB is better if you buy during RBI's primary issuance and hold till maturity. You get 2.5% annual interest AND zero capital gains tax. Important (Budget 2026):If you buy SGB from the secondary market (stock exchange), you'll pay 12.5% LTCG even at maturity. Gold ETF makes sense for liquidity, trading, or if you missed the primary SGB issuance.
Can NRIs invest in SGB?
No. Sovereign Gold Bonds are only for resident Indians. NRIs can invest in Gold ETFs through their NRE/NRO demat accounts, or buy physical gold during India visits.
When is the next SGB issue?
Note: RBI has not issued any new SGB since February 2024. Check RBI websitefor future announcements. You can buy existing SGBs on NSE/BSE, but you'll lose the tax exemption benefit (Budget 2026 change).
Is digital gold safe?
Digital gold is not regulated by SEBI or RBI. Your gold is held by private companies (MMTC-PAMP, Augmont). If the platform shuts down, recovery may be difficult. For larger amounts, prefer SGBs or Gold ETFs.
What happens to SGB if gold price falls?
SGB redemption is at prevailing gold prices. If gold price falls, you get less. However, you still get the 2.5% annual interest which provides some cushion. Remember, gold is long-term - don't panic at short-term falls.
Can I convert digital gold to physical?
Yes, most digital gold platforms (Paytm, PhonePe) allow conversion to physical gold coins/bars. Minimum is usually 1-2 grams. You pay delivery charges. But honestly, if you want physical, just buy from a bank directly.
Is 22K gold a good investment?
No. 22K gold is 91.6% pure (mixed with other metals for durability). You lose value on the impure portion. Always buy 24K (99.9% pure) for investment. 22K is only for jewelry you plan to wear.
How to do SIP in gold?
You can set up Gold ETF SIP through your broker (Zerodha, Groww). For digital gold, apps like Paytm offer daily/weekly/monthly auto-invest. SGBs don't support SIP - you buy during tranche windows.
Final Verdict: How to Invest in Gold
1. For long-term (8+ years): Buy SGB during RBI's primary issuance for tax-free maturity. (Note: No new issuance since Feb 2024)
2. For regular SIP or trading: Use Gold ETFs via your broker. 12.5% LTCG after 1 year.
3. Avoid physical gold: Making charges and storage costs kill returns.
4. Keep allocation to 5-10%: Gold is insurance, not the main engine.